October 2026 Bond Market Comments
Yields Fall Sharply in October but Remain Higher YTD, Fed Holds in Advance of Midterm Elections
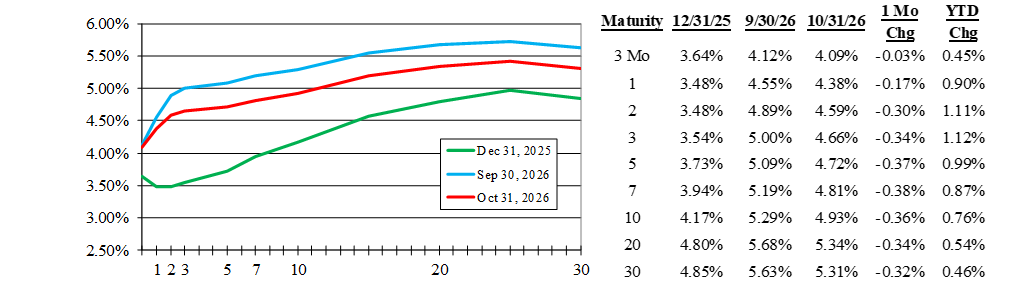
Treasury yields declined across the curve in October, reversing a large portion of September’s significant increase. The 10yr Treasury yield ended October at 4.93%, 36 bps lower for the month but still 76 bps higher YTD. The 2s10s Treasury slope also modestly flattened by 6 bps as the 2yr fell 30 bps in October. Solid 10yr and 30yr auction demand at elevated yields supported Treasuries in early October. Additionally, the Treasury market was buoyed by the release of lower September nonfarm payrolls (+29k vs. +90k estimate) as well as risk aversion tied to a perceived softening in AI-related capex spending. For its part, the Fed opted to hold its policy rate at 3.75–4.00% in a 10–2 vote, with Cook and Hammack dissenting in favor of a hike. The Fed portrayed this hold as more of a “skip” than a lasting pause, which some attribute in part to the upcoming U.S. midterm elections, and noted that the focus remained on fighting inflation. Core PCE inflation YoY was reported at 3.1%, up from 3.0% and well above the Fed’s 2% target. Headline PCE, which includes energy, rose to 3.6% from 3.4%. Fed Chair Warsh, a longtime champion of less forward guidance, also announced changes to the Fed meeting calendar. The Fed has held eight meetings per year with rate decisions but will move to seven such meetings in 2027 and six in 2028. Strategy-only meetings (one in 2027, two in 2028) will carry no rate vote or statement. Deficits remain a concern globally and domestically. The U.S. ended its fiscal year on September 30 with debt/GDP above 100%, the highest since 1946 in the wake of WWII spending.
Treasury Yields
AI Drives Corporate Spread Widening
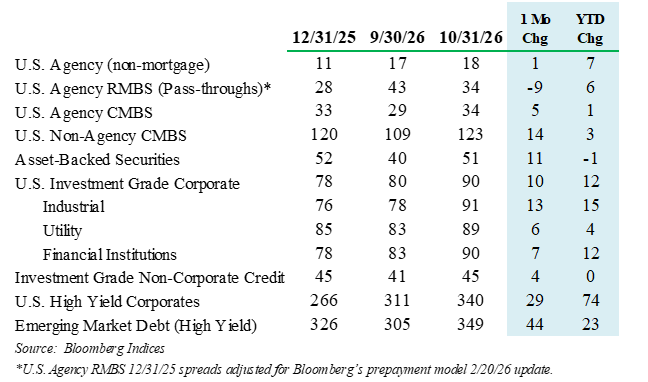
IG Corporate spreads finished at +90 bps, 10 bps wider in October, reaching their highest level since March. Subsector performance varied as Communications and Technology underperformed Energy and Financials. Microsoft, the lone hyperscaler to avoid issuing debt during the recent AI capex boom, sold $25B of bonds in October, marking its first issuance since 2017. HY Corporates and EM HY underperformed amid risk aversion.
Strong Absolute Returns, Mostly Negative Excess Returns
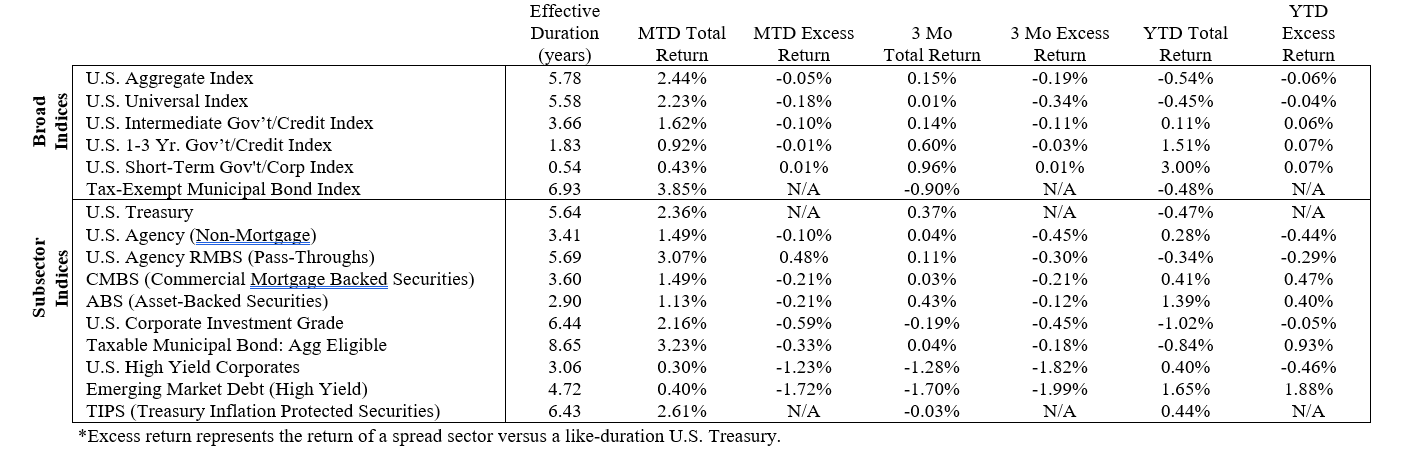
The Agg Index returned 2.44% in October. Absolute returns were positive across the board. However, excess returns were negative across the board too, save Agy RMBS, which rebounded from notable September underperformance. Tax-exempt municipals also rebounded sharply in October following September weakness.
Option-Adjusted Spreads (in bps)
Returns of Selected Bloomberg Indicies and Subsectors
Disclosures
Information in this document regarding market or economic trends, or the factors influencing historical or future performance, reflects the opinions of management as of the date of this document. These statements should not be relied upon for any other purpose. This is not a complete analysis of every material fact regarding any company, industry or security. The information has been obtained from sources we consider to be reliable, but we cannot guarantee the accuracy. Past performance is not a guarantee of future results.
Fixed income is generally considered to be a more conservative investment than stocks, but bonds and other fixed income investments still carry a variety of risks such as interest rate risk, credit risk, inflation risk, and liquidity risk. In a rising interest rate environment, the value of fixed- income securities generally decline and conversely, in a falling interest rate environment, the value of fixed-income securities generally increase. High yield securities may be subject to heightened market, interest rate or credit risk and should not be purchased solely because of the stated yield.
Treasury yields are the interest rates that the U.S. government pays to borrow money for varying periods of time.
Option-adjusted spread is the difference between the yield of a security that pays fixed interest payments and the current U.S. Treasury rates, which represents the rate of return on a risk-free investment.
The Bloomberg U.S. Aggregate Bond Index is an index comprised of approximately 6000 publicly traded bonds including U.S. Government, mortgage-backed, corporate, and Yankee bonds with an average maturity of approximately 10 years.
The Bloomberg Government/Credit Index is a combination of the Government Index which measures government-bond general and Treasury funds, and the Credit Bond Index, which is a market value-weighted index which tracks the returns of all publicly issued, fixed-rate, nonconvertible, dollar-denominated, SEC registered, investment grade Corporate Debt.
The Bloomberg Intermediate U.S. Government/Credit Bond Index is a combination of the Government Index which measures government-bond general and Treasury funds, and the Credit Bond Index, which is a market value-weighted index which tracks the returns of all publicly issued, fixed-rate, nonconvertible, dollar-denominated, SEC registered, investment grade Corporate Debt with maturities between one and ten years.
The Bloomberg 1-3 Year U.S. Government/Credit Bond Index is a combination of the Government Index which measures government-bond general and Treasury funds, and the Credit Bond Index, which is a market value-weighted index which tracks the returns of all publicly issued, fixed-rate, nonconvertible, dollar-denominated, SEC registered, investment grade Corporate Debt with maturities between zero and three years.
The Bloomberg U.S. Treasury Index includes public obligations of the U.S. Treasury. Treasury bills are excluded by the maturity constraint of at least one year but are part of a separate Short Treasury Index. In addition, certain special issues, such as state and local government series bonds (SLGs), as well as U.S. Treasury TIPS, are excluded. STRIPS are excluded from the index because their inclusion would result in double- counting. Securities in the Index roll up to the U.S. Aggregate, U.S. Universal, and Global Aggregate Indices. The U.S. Treasury Index was launched on January 1, 1973.
U.S. Agency: This index is the U.S. Agency component of the U.S. Government/Credit index. Publicly issued debt of U.S. Government agencies, quasi-federal corporations, and corporate or foreign debt guaranteed by the U.S. Government (such as USAID securities). The largest issues are Fannie Mae, Freddie Mac, and the Federal Home Loan Bank System (FHLB). The index includes both callable and non-callable agency securities.
U.S Corporate – Investment Grade: This index is the Corporate component of the U.S. Credit index. It includes publicly issued U.S. corporate and specified foreign debentures and secured notes that meet the specified maturity, liquidity, and quality requirements. To qualify, bonds must be SEC-registered.
CMBS (Commercial Mortgage-Backed Securities): This index is the CMBS component of the U.S. Aggregate index. The Bloomberg CMBS ERISA-Eligible Index is the ERISA-eligible component of the Bloomberg CMBS Index. This index, which includes investment grade securities that are ERISA eligible under the underwriter’s exemption, is the only CMBS sector that is included in the U.S. Aggregate Index.
MBS (Mortgage-Backed Securities): This index is the U.S. MBS component of the U.S. Aggregate index. The MBS Index covers the mortgage- backed pass-through securities of Ginnie Mae (GNMA), Fannie Mae (FNMA), and Freddie Mac (FHLMC). The MBS Index is formed by grouping the universe of over 600,000 individual fixed rate MBS pools into approximately 3,500 generic aggregates.
ABS (Asset-Backed Securities): This index is the ABS component of the U.S. Aggregate index. The ABS index has three subsectors: credit and charge cards, autos, and utility. The index includes pass-through, bullet, and controlled amortization structures. The ABS Index includes only the senior class of each ABS issue and the ERISA-eligible B and C tranche. The Manufactured Housing sector was removed as of January 1, 2008, and the Home Equity Loan sector was removed as of October 1, 2009.
Corporate High Yield: The Bloomberg U.S. High Yield Index covers the universe of fixed rate, non-investment grade debt. Eurobonds and debt issues from countries designated as emerging markets (sovereign rating of Baa1/BBB+/BBB+ and below using the middle of Moody’s, S&P, and Fitch) are excluded, but Canadian and global bonds (SEC registered) of issuers in non-EMG countries are included. Original issue zeroes, step-up coupon structures, 144-As and pay-in-kind bonds (PIKs, as of October 1, 2009) are also included.
Emerging Market: Bloomberg uses a fixed list of countries defined as emerging markets countries for index inclusion purposes that is based on World Bank Income group definitions (Low/Middle), IMF country classifications (Non-Advanced Economies), and other advanced economies that may be less accessible or investable for global debt investors.
The Bloomberg Municipal Bond Index is a broad-based, total-return index. The bonds are all investment-grade, tax-exempt, and fixed-rate securities with long-term maturities (greater than 2 years). They are selected from issues larger than $50 million.
The Bloomberg TIPS Index consists of Treasury Inflation Protected Securities (TIPS). TIPS are securities whose principal is tied to the Consumer Price Index. TIPS pay interest semi-annually, based on the fixed rate applied to the adjusted principal.
Ratings are measured on a scale that ranges from AAA or Aaa (highest) to D or C (lowest). Investment grade investments are those rated from highest down to BBB- or Baa3.
This is not a complete analysis of every material fact regarding any company, industry or security. The information has been obtained from sources we consider to be reliable, but we cannot guarantee the accuracy. Indices are unmanaged and are not available for direct investment.
©2026 Robert W. Baird & Co. Incorporated.